
Crunchfish has received an Intention to Grant from the European Patent Office (EPO) for its patent application covering local transfer of digital value between a mobile wallet and an EMV-compatible smart card. The technology covered by the allowed claims enables a payment card to be topped up directly from a mobile device, with the local transfer capable of being performed without network connectivity. Value held on the card can subsequently be transferred to another mobile device or used for payments at a point of sale. The mechanism is applicable to both Immediate and Governed Offline payment architectures and can become relevant to potential Digital Euro implementations.
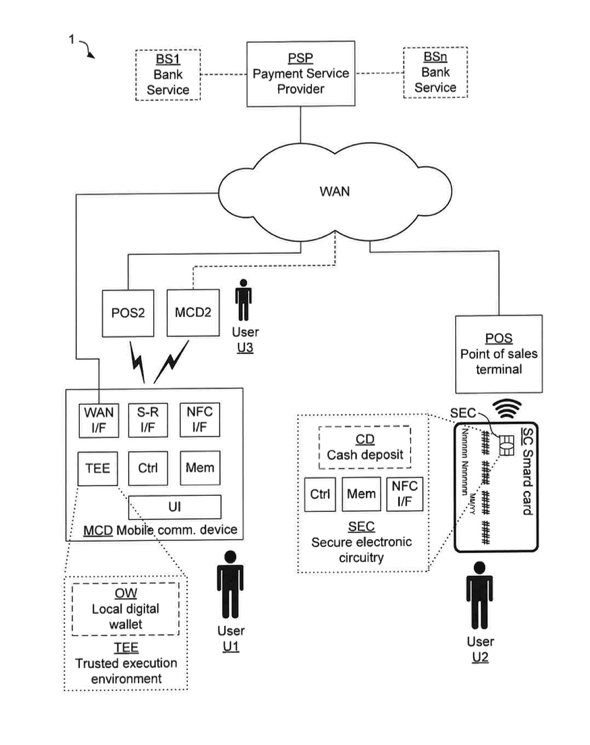
The European patent application, Transfer of Digital Cash Between Mobile Communication Device and Smart Card, covers a value transfer system in which a balance amount is transferred locally between a mobile wallet and an EMV-compatible smart card. The locally held balance of the sender is reduced and the corresponding balance of the receiver is increased. The independent claim supports transfers in both directions, allowing a payment card to receive value from a mobile wallet as well as transfer value back to a mobile wallet.
This enables an EMV-compatible payment card to be topped up with digital value directly from a mobile device. As the claimed transfer takes place over a local point-to-point connection directly between the devices, it can be performed without network connectivity. The card can therefore act as a portable carrier of digital value. Once topped up, value held on the card can subsequently be transferred locally to another mobile device.
The patent application also includes dependent claims covering the use of the smart card's locally held cash deposit to make digital payments at a point-of-sale terminal. The POS receives the digital payment from the card's cash deposit and communicates it to a payment service provider, which causes settlement by transferring funds from an account associated with the cardholder to an account associated with the Merchant with the POS.
The local value-transfer mechanism can be applied to both Immediate Offline and Governed Offline payment architectures. In an Immediate Offline implementation, the locally transferred value can represent the digital money itself. In a Governed Offline implementation, the locally transferred value can represent spendable offline value backed by money reserved in the underlying monetary system, with reconciliation and settlement taking place when connectivity is available.
This distinction also makes the patent relevant to potential digital euro implementations involving transfers between mobile wallets and EMV-compatible payment cards. The claimed local transfer mechanism does not prescribe whether the transferred local value represents digital money itself, as in Immediate Offline, or spendable offline value backed by reserved money, as in Crunchfish's Governed Offline architecture. The same local balance-transfer mechanism can therefore support either approach.
"This invention enables an EMV-compatible payment card to be topped up with digital value directly from a mobile phone, even when offline. The value can subsequently be transferred to another mobile or used for payments at a point of sale. Importantly, the mechanism is applicable whether the locally transferred value represents the money itself in an Immediate Offline architecture or spendable offline value backed by reserved money in Governed Offline. This may become relevant for the Digital Euro, where offline payments and compatibility with existing payment infrastructure are important considerations," says Joachim Samuelsson, CEO of Crunchfish.
The smart card specified in the allowed claims contains secure electronic circuitry on a credit-card-sized substrate, accommodates a locally held cash deposit and is compatible with EMV payments. The claims therefore combine local digital value storage and transfer with compatibility with the established EMV payment-card environment.
The EPO's Intention to Grant concerns European patent application EP 22 746 356.9, entitled Transfer of Digital Cash Between Mobile Communication Device and Smart Card. The application has priority from January 29, 2021. The EPO has indicated that it intends to grant the patent based on the current set of 16 claims, subject to completion of the formal grant procedure. Corresponding patent applications are pending in the United States, India and Brazil.
The patent application is part of Crunchfish's growing intellectual property portfolio within offline payments and complements the company's other patents relating to secure offline payments, interoperability and settlement.
For more information, please contact:
Joachim Samuelsson, CEO of Crunchfish AB
+46 708 46 47 88
joachim.samuelsson@crunchfish.com
This information is Crunchfish AB obliged to publish in accordance with the EU Market Abuse Regulation. The information was provided by the contact person above for publication on 13thOctober, 2026 at 15:00 CET.
Västra Hamnen Corporate Finance AB is the Certified Adviser. Email: ca@vhcorp.se. Telephone +46 40 200 250.
About Crunchfish - crunchfish.com
Crunchfish is a deep fintech company developing governed offline payments technology for payment systems, banks, and payment applications. The company enables offline payments as a Layer-2 solution on top of existing payment systems, allowing transactions to be executed without connectivity while ledger authority and settlement remain unchanged. Through a reservation-based model, resilience is achieved without creating parallel forms of money or unmanaged credit risk. Crunchfish's architecture is patented and enables interoperability across multiple payment systems and markets. The solution strengthens system stability while also supporting economic incentives by ensuring that liquidity backing offline payments remains within the regulated financial system.
