
Strong revenue growth of +34.9% YoY with record R$8.5bn portfolio on a flat cost base, as AI moves from deployment to scale
São Paulo, October 29th, 2026
Key Highlights - Q3-26
Portfolio
•Origination held near record levels at R$1.13bn in Q3-26 (+15.0% YoY and -0.5% QoQ), broadly stable versus Q2-26.
•Portfolio reached a record R$8.5bn (+26.8% YoY and +5.1% QoQ), once again advancing above our 25%+ annual growth target. This reflects the compounding effect of sustained origination across our business units despite Selic remaining at high levels.
Financials
•Revenues reached a record R$728.3mn (+34.9% YoY and +0.7% QoQ). Sequential growth was moderated by a lower contribution from inflation indexation in our Home Equity portfolio. Excluding this effect, revenues would have grown 7.0% QoQ, driven by continued portfolio expansion and improved commission rates.
•Gross Profit reached R$251.6mn (+22.0% YoY and -7.4% QoQ), with a Gross Profit Margin of 34.6% (37.6% in Q2). The sequential decline reflects the reversal of the Q2 inflation tailwind, a calendar accrual mismatch in the cost of funding and slightly higher cost of credit associated with the expanding portfolio.
•Operating Costs and Expenses totaled R$304.6mn (+5.8% YoY and -0.2% QoQ), expanding significantly below revenue growth and maintaining an essentially flat cost base even as we scale our portfolio to new record levels. Automation and AI execution continued to unlock structural capacity across the business, ranging from automated credit analysis and loan formalization to AI-supported first-line customer support and automated creation of software pull requests ("PRs"), among other efficiency initiatives.
•Operating loss totaled R$53.0mn (vs. R$81.8mn in Q3-25 and R$33.7mn in Q2-26), underscoring structural cost base improvements on a year-over-year basis while we continue investing in growth acceleration. Sequentially, performance was impacted by the Gross Profit compression observed in the quarter.
Operations
• Origination activity remained essentially stable in Q3-26. Auto Finance delivered +5.3% QoQ growth, while Private Employees Payroll Loans grew 3.8%; Auto Equity and Home Equity regained momentum as the quarter progressed after a softer start. With AI agents operating across the platform, our focus is now on improving precision, autonomy and conversion, while deploying new agentic use cases.
• We continued to scale our AI Platform throughout all business units in Q3-26, as our AI agenda matures into a fully integrated, company-wide operating model, with AI agents running in production across end-to-end origination, underwriting, collections, customer service, back office and software development. Key operational milestones include:
-CX & Collections: First-line credit chat is now fully AI-driven, scaling seamlessly alongside the continued portfolio expansion. In the 1-30 DPD collections bucket, the agent is fully operational, enabling us to advance efforts into the 31-60 band, where coverage has reached 20% of total volume. As agents mature, they are driving a growing share of overall debt recovery with significant QoQ efficiency gains.
-Sales & Origination: our AI sales agent now out-converts human consultants in its target segments while scaling fast. Built on our new architecture, the agent guides first-time Auto Equity customers from offers through completed documentation directly on WhatsApp, handling identity, income and residence verification end to end. As we progressively direct more volume to the channel and refine agent capabilities, fully automated origination is ramping up, marked by early momentum in September.
-Back Office & Underwriting: in Auto Finance, our underwriting agent now automatically processes over 50% of the applications, significantly reducing turnaround times and manual touchpoints. AI-support across channel operations unlocked substantial operational leverage, enabling small teams to manage extensive dealer networks and doubling commercial revenue per headcount YoY. In addition, AI-driven profitability models now analyze granular store-level data to optimize commercial incentives.
-Software Development: AI-assisted PRs accounted for 93% of all PRs in September, with PRs per active developer reaching 19.3 (almost double the 2025 monthly average). Median commit-to-merge lead time stayed flat throughout the quarter at 3.9 hours, demonstrating significant productivity gains given the higher PR volume generated, while the Change Failure Rate (CFR) stayed below 1% as we continue migrating more of the development cycle to the Creditas harness.
Q3-26 confirms the momentum we've been building, with annualized metrics reflecting the structural strength of our business model: R$4.5bn in annualized origination, approaching an R$8.9bn year-end portfolio (+25% YoY), alongside annualized revenues surpassing R$2.9bn. Our run-rate operating loss stood significantly below last year's level despite growth acceleration - a trajectory expected to improve further over the full year as quarterly volatility smooths out. The ongoing expansion of our earning asset base continues to outpace operating costs, reinforcing the structural leverage built into our model. With AI integration moving deeper into core execution across the company, we are strengthening unit economics and accelerating our path toward sustained, profitable scale.
Productivity gains are not just continuing; they are accelerating. Annualized revenue per employee reached R$1.9mn, roughly 23x higher than in 2019, and it is the pace of that climb that stands out: after growing 22% across all of 2025, revenue per employee is already up 68% versus that full-year baseline. This inflection reflects AI deployments compounding into structural productivity gains, not only incremental efficiency.
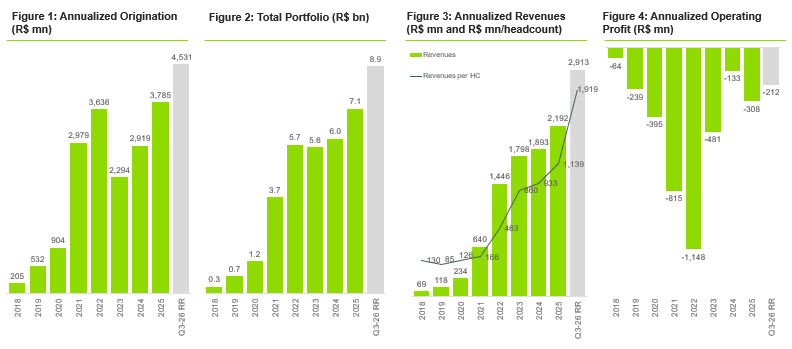
Figures 1, 2, 3 & 4: Annualized results evolution
Third Quarter Financial & Operating Results
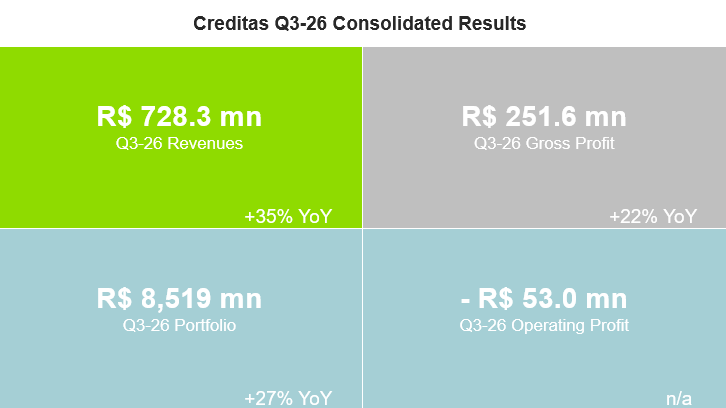
Figure 5: Summarized results
In Q3-26, origination totaled R$1,133mn, broadly stable versus Q2-26, while Portfolio reached a record R$8.5bn, once again advancing above our 25%+ annual growth target, continuing its compounding trajectory across all core credit verticals (see Figure 6 and Figure 7).
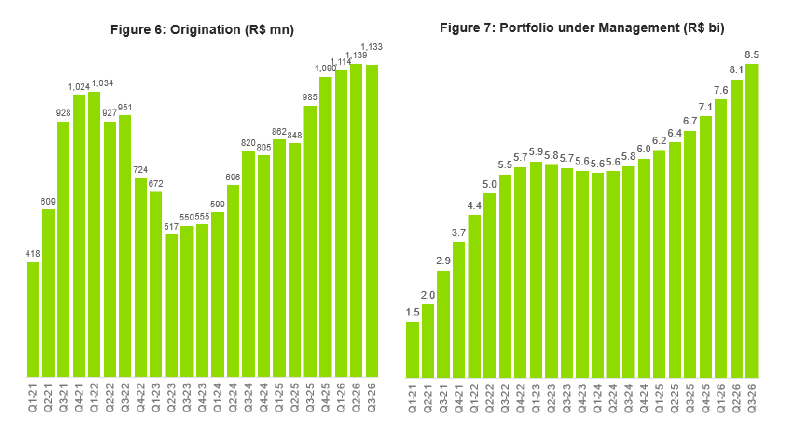
Figures 6 & 7: Origination and Portfolio under Management
The continued expansion of our Portfolio supported Revenue growth to a new record R$728mn (+34.9% YoY and +0.7% QoQ, see Figure 8), marking our fourth consecutive quarter of top-line growth. Portfolio growth and the associated spread accrual, alongside higher fees and commissions, helped offset a lower contribution from inflation-linked income in Home Equity relative to Q2. Gross Profit stood at R$252mn (+22.0% YoY and -7.4% QoQ), translating into a 34.6% Gross Profit Margin (see Figure 9). Sequentially, the margin variation was largely driven by market and calendar dynamics - specifically lower IPCA accrual and higher funding costs resulting from a higher business day count in the quarter. Cost of credit also increased, in line with the natural maturation and expansion of our loan book. More importantly, gross profit at the cohort levels, which eliminates the time-impact of growth and seasonal behavior, remains above our 40% target.
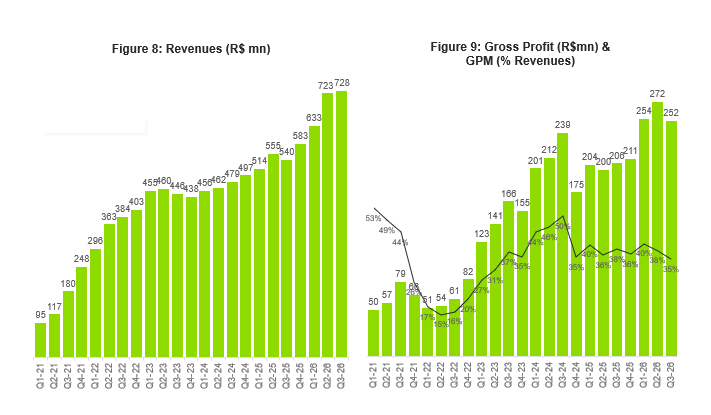
Figures 8 & 9: Revenues and Gross Profit & GPM
Operating Costs and Expenses (see Figure 10) totaled R$304.6mn (+5.8% YoY), growing significantly below our 34.9% YoY revenue expansion and declining to 41.8% of revenue in Q3-26 (from 53.3% in Q3-25). Customer Acquisition Costs declined in absolute terms, reflecting the continued efficiency gains from AI-driven automation across sales and underwriting. General and administrative expenses remained broadly stable in nominal terms during the quarter, continuing to decline as a share of revenue. Annualized revenue per headcount reached R$1.9mn, up from R$1.7mn in Q2-26, continuing to incorporate the structural productivity gains that have characterized our platform's evolution (see Figure 11).
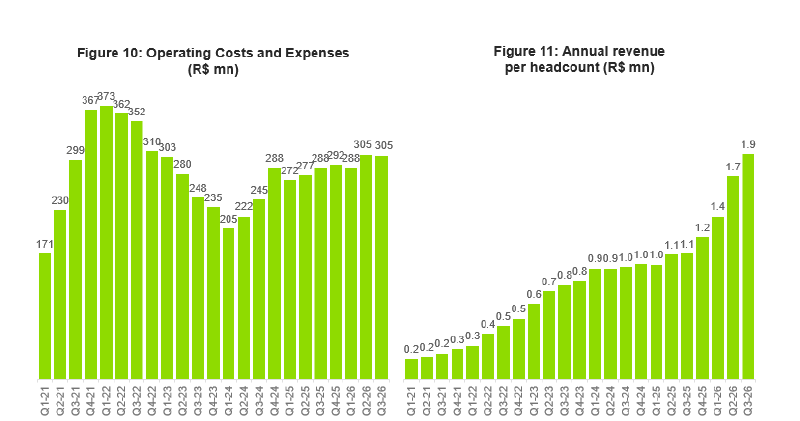
Figures 10 & 11: Operating Costs and Expenses, Annual Revenue per Headcount
Operating loss totaled R$53.0mn in Q3-26 (see Figure 12), compared to R$33.7mn in Q2-26, reflecting the lower gross profit in the quarter related to the calendar impacts mentioned above. On a year-over-year basis, operating loss was 35.2% lower than in Q3-25 (R$81.8mn) and remained lower than in any quarter of 2025 - a signal that, even as quarterly results fluctuate, the trajectory of our operation remains favorable. Net loss for the quarter totaled R$108.4mn (see Figure 13), compared to R$66.9mn in Q2-26, driven primarily by non-cash accounting adjustments recognized in the quarter. Importantly, we maintained a neutral cash flow position, which continues to enable us to fund our growth internally without relying on external equity capital - a key pillar of our long-term strategy. The Q3-26 results reinforce our structural playbook: scaling the platform at a 25%+ portfolio growth rate, expanding revenues, and leveraging AI-driven efficiency to progressively dilute operating costs.
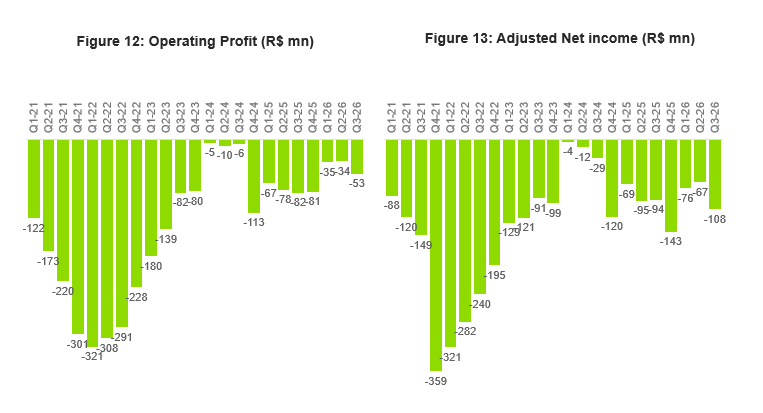
Figures 12 & 13: Operating Profit and Adjusted Net Income
Business Unit Performance
Auto Equity
Auto Equity, our flagship product, reached a new record portfolio size in Q3-26, increasing 20.3% YoY. Growth was underpinned by expanding automated touchpoints across the customer lifecycle, enabling us to continue reducing customer acquisition costs and strengthen unit economics. Looking ahead, ongoing initiatives in dynamic pricing and improved platform architecture position the product to sustain disciplined expansion with increasing operational leverage.
Home Equity
Home Equity's portfolio grew 26.2% YoY in Q3-26, continuing to solidify our market-leading position. Growth was supported by an optimized digital journey and the deployment of an in-house AI commercial agent to qualify all incoming leads, driving faster response. Looking ahead, modernizing our core origination flow, combining deeper channel partnerships and returning customer engagement, lays the groundwork to accelerate origination momentum.
Private Employees Payroll Loans
Our private payroll loan portfolio continued to expand in Q3-26 (+33.9% YoY), accompanied by sequential QoQ origination growth while maintaining addressable private employee coverage at approximately 21% (vs. 22% in Q2-26). Automatic job-to-job portability through upgraded regulatory rails allows active loans to transfer to new employers, structurally mitigating credit risk over time. With loan formalization now virtually fully automated, our focus remains on scaling AI-driven execution across origination and servicing.
Auto Finance
Auto Finance prioritized profitability in Q3-26, tightening income-commitment limits and refining dealer segmentation while still delivering robust quarterly origination and expanding its portfolio by more than 50% YoY. Growth was driven by disciplined commercial execution and higher partner engagement, with dealer activation and productivity continuing to improve across key regions. Looking ahead, we remain focused on risk-adjusted margins, supported by regionalized pricing and targeted credit policies.
Insurance
We continue to advance our insurance strategy, reinforcing Creditas' position as the largest independent online insurance broker in Brazil. Our portfolio remained broadly stable in the quarter, anchored by a growing renewable base. Ecosystem integration continued to progress, driven by higher credit life insurance penetration in Auto Finance and Private Payroll. Productivity is improving, supported by our AI renewal agent and the automation of back-office tasks. Looking ahead, we continue to pursue multiple avenues to unlock the product's full potential and position insurance as a strategic pillar to drive further platform scale in the coming years.
Business Outlook
Creditas further consolidates its growth trajectory, with AI and automation increasingly embedded end to end across the customer and credit lifecycle. In Q3-26, these capabilities delivered structural productivity gains across all business units, laying the groundwork for sustained expansion. Looking ahead, we remain committed to our 25%+ annual growth target, consistently balancing disciplined credit underwriting with operating leverage toward sustainable profitability. In light of recent developments in Brazilian market conditions, we remain prudent in our approach to credit and funding, closely monitoring the macroeconomic environment and retaining flexibility to adapt our 2027 strategy as needed.
For further information, please contact:
Creditas:
Sergio Furio / Shirlei Silva
CEO / Director of Investor Relations
E-mail: Investor-relations@creditas.com
Or visit www.creditas.com and ir.creditas.com
