
Sustainability Statement
General disclosures
Basis for preparation
NORTHAMPTON, MA / ACCESS Newswire / November 18, 2026 / The Sofidel Group's Consolidated Sustainability Statement (hereinafter also the "Sustainability Statement") has been prepared taking into account developments in the European sustainability reporting regulatory framework and the gradual alignment with the European Sustainability Reporting Standards (ESRS) introduced under Directive (EU) 2022/2464 - the Corporate Sustainability Reporting Directive (CSRD).
The Statement was prepared in a context characterisedby both a two-year deferral of the mandatory application of the CSRD for the Sofidel Group and an ongoing review at the date of preparation of this document. In particular:
- The application of the ESRS is not yet mandatory for the Sofidel Group as a result of Directive (EU) 2025/794 ('Stopthe-Clock' Directive), which postponed its application until the 2027 financial year;
- the ESRS framework is currently undergoing a review which was announced but had not yet been finalised at the time of drafting this Sustainability Statement;
- with Commission Recommendation (EU) 2025/1710, the European Commission recommended, on a transitional and short-term basis, the use of the VSME standard - voluntary sustainability reporting standard for non-listed small and medium-sized enterprises. With reference to the current draft prepared by EFRAG, large undertakings can also adopt it on a voluntary basis; however, this decision is at the discretion of the organisation itself.
In this context, the Sofidel Group adopted a gradual and proportionate approach to sustainability reporting, recognising its central role as a driver of transparency, accountability and structured dialogue with stakeholders.
Sofidel therefore chose to prepare its sustainability discloures in accordance with the VSME standard (option B: Basic Module and Comprehensive Module), adopted as the minimum reference framework for preparation of the information, and to include it within the Management report, in order to ensure consistency, comparability and an integrated overview with the e financial information, in line with the voluntary reporting approach adopted over the years as well as with a view to progressive alignment with future regulatory requirements.
The VSME standard was selectively supplemented with disclosure requirements and indicators derived from the ESRS, the GRI standards and the SASB standards, where deemed necessary to adequately represent the specific characteristics of the Group's business model and its interactions with sustainability topics.
The level of alignment with the various reference standards and the location of the relevant information within the document are set out in the Content Index section, which lists, for each applicable standard, the relevant disclosure requirement and the location of the corresponding disclosure within the text.
Structure of the sustainability statement
The Group's Sustainability Statement is structured into four main sections, with a view to gradually aligning with the requirements of the CSRD:
- General disclosures;
- Environmental information;
- Social information;
- Business conduct information.
In particular, this section of the Management report presents the environmental, social and governance topics that are material for the Group, taking into account the results of the double materiality analysis described in the dedicated section.
In the relevant sections, the following information is provided for each material topic:
- a summary of the material impacts, risks and opportunities (IROs) at sub-topic and sub-sub-topic level;
- key management measures and action plans;
- the relevant metrics for understanding the Group's performance.
Given that the Sustainability Statement is included within the Management Report, certain information required by the adopted standards is provided by way of incorporation by reference, through cross-references to specific sections of the Management Report (business model and development factors, governance and risk management system).
Sustainable Finance
According to the European Investment Bank, sustainable finance involves including environmental, social and governance considerations in investment decisions, channelling capital towards activities and projects that are sustainable in the long term. It plays a key role in achieving the objectives of the European Green Deal, which aims to promote the green transition, i.e. the shift towards a more sustainable economy through sustainable technologies, industry and transport.
Within this framework, in 2023 Sofidel completed four medium/long-term financing transactions with leading European institutions, structured as Sustainability-Linked Loans (SLL) in accordance with the Sustainability-Linked Loan Principles defined by the Loan Market Association (LMA).
These loans were intended to strengthen the Group's financial structure and, at the same time, to promote and monitor the adoption of good environmental and social practices through specific sustainability indicators. Following the significant acquisitions carried out in the United States between 2024 and 2025, the Group, in agreement with its lenders, updated the SPTs (Sustainability Performance Targets) associated with the Sustainability Linked Loans, while keeping the KPIs defined at signing unchanged. This enabled the realignment of the sustainability indicators with the Group's new scope of operations.
Reporting period, scope, comparability of data and estimates
The reporting period covered by the Sustainability Statement corresponds to the 2025 financial year (1 January to 31 December 2025). This Statement has been prepared on a consolidated basis, and the scope of reporting corresponds to the scope of consolidation of the Sofidel Group's consolidated financial statements. With regard to the assets acquired from Royal Interco, LLC ('Royal Paper'), their performances are included in reporting from the date on which they are consolidated in the financial statements. A detailed list of the Group's sites included in the scope of reporting, together with their geographical coordinates, is provided in the Appendix section of the Sustainability Statement.
The reporting methodology adopted ensures, as far as possible, comparability of information over time. Where changes or methodological refinements have occurred, as well as updates to the measurement criteria, data for prior financial years have been restated, where applicable, to ensure o ensure consistent Scope of assurance and comparable presentation. These cases are clearly identified and described in the relevant sections of the document. Where new performance indicators are introduced from 2025 onwards, or where methodological refinements cannot be applied retrospectively to data for the 2024 and 2023 financial years, the symbol '-' is shown in the tables. The value '0' is used to indicate that the indicator has a value of zero for the relevant financial year.
The quantitative information has been prepared on the basis of the data available at the time of preparation. Where necessary and where indicated, estimates and assumptions have been used, based on methodologies deemed appropriate and consistent with market best practice and with the principles of reliability, clarity and fair presentation of information.
In preparing this Sustainability Statement, Sofidel has not exercised the option to omit information classified as sensitive.
Scope of assurance
The qualitative and quantitative disclosure prepared in accordance with the VSME standard, reported in this Sustainability Statement, was subjected to limited assurance by EY S.p.A., according with the principles of the ISAE 3000 International Standard on Assurance Engagements (Revised) - Assurance Engagements Other than Audits or Reviews of Historical Financial Information - ('ISAE 3000 Revised'), issued by the International Auditing and Assurance Standards Board (IAASB).
The complete list of VSME disclosure requirements reported, indicating their location within the document, is set out in the VSME Standard Content Index, under the Content Index section.
Quantitative indicators not linked to any VSME disclosure, reported on the same pages indicated in the VSME Content Index, are not subject to limited assurance by EY S.p.A.
The list of these indicators and supplementary information, which do not relate to any VSME disclosure, derived from the ESRS, the GRI standards and the SASB standards is set out separately in the Content Index: Other Standards - ESRS, GRI, SASB, included in the Content Index section.
In accordance with the scope of the engagement, the double materiality analysis conducted by the Group,although it represents a central element of the reporting process and the identification of material topics, is not subject to limited assurance by EY S.p.A. The methodology used and the results of the analysis are set out in the dedicated section.
Stakeholder engagement
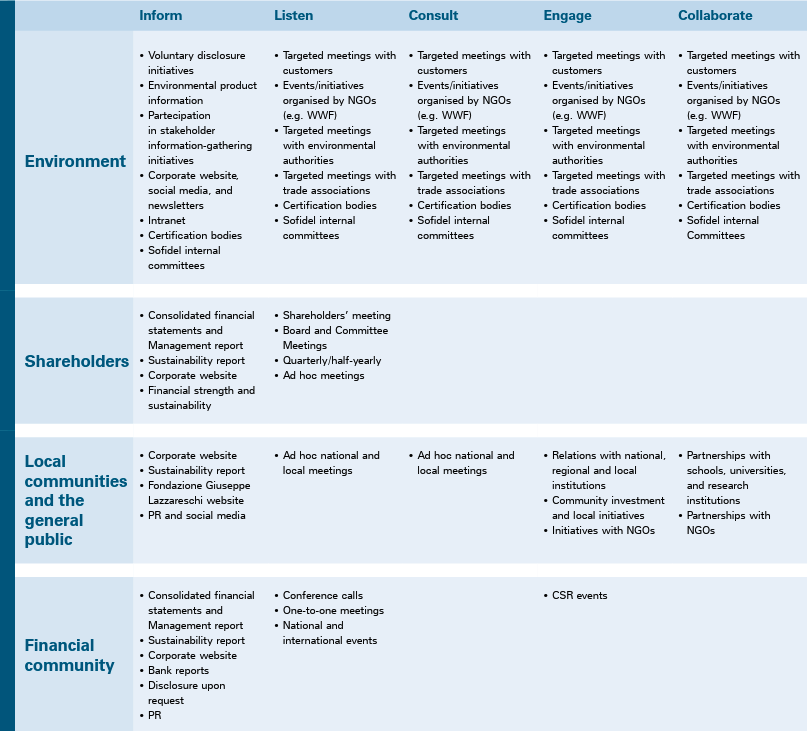
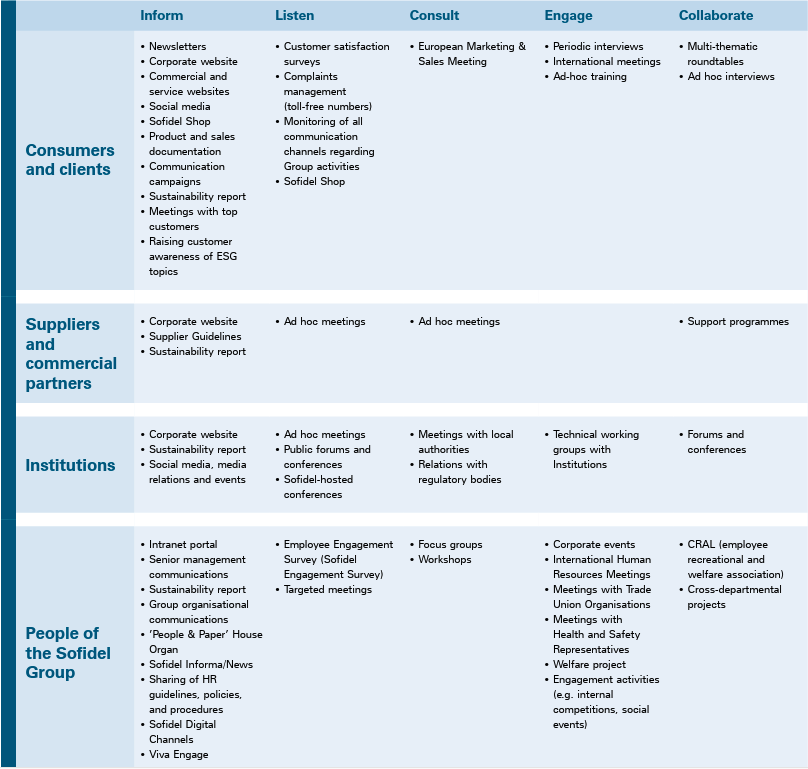
Throughout 2025, the Group maintained an ongoing dialogue with its stakeholders on material topics, using engagement channels and tools tailored to the nature of the topics, the level of engagement, and the specific context.
Find more stories and multimedia from Sofidel Group at 3blmedia.com.
Contact Info:
Spokesperson: Sofidel Group
Website: https://www.3blmedia.com/profiles/sofidel
Email: info@3blmedia.com
SOURCE: Sofidel Group
View the original press release on ACCESS Newswire:
https://www.accessnewswire.com/newsroom/en/paper-and-packaging/sofidel-integrated-report-2025-sustainability-statement-and-stakeholder-engagem-1253427