

July - September
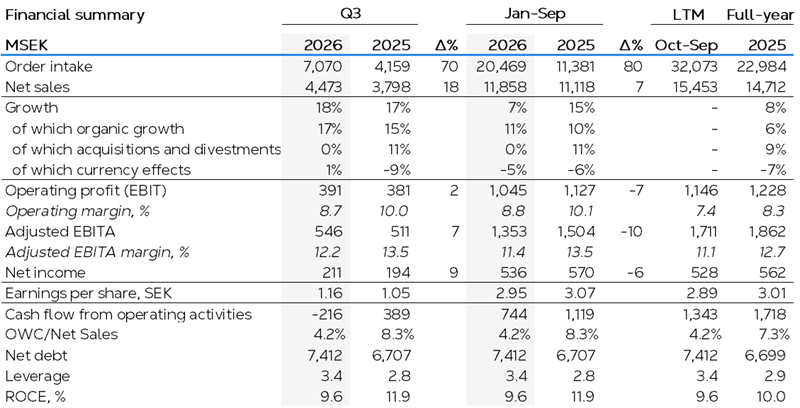
Order intake increased +70%, driven by strong demand in Data Center Technologies (DCT) and AirTech.
Net sales increased +18%, driven by all business areas, particularly AirTech. In AirTech growth was driven primarily by Americas and APAC. DCT grew through continued backlog execution and higher production volumes, while FoodTech recorded slight growth.
The adjusted EBITA margin declined. AirTech's margin rose on higher volumes, favorable mix and cost savings. DCT's margin fell, reflecting changed product mix, component shortages and ramp-up inefficiencies. FoodTech's margin declined though remained strong.
Negative cash flow from operating activities, mainly explained by inventory build-up within DCT though somewhat mitigated by advances from customers.
OWC/net sales improved to 4.2%, well below the target range of 13-10%.
Leverage of 3.4x (3.2x in Q2 2026), mainly due to negative cash flow and higher lease liabilities.
Earnings per share amounted to SEK 1.16 (1.05).
 ?
CEO comments
We continued to see significant order growth across the Group in the third quarter, with an increase of 70% demonstrating Munters strong market position. The order intake is beginning to translate into higher net sales as factory utilization improves. However, our financial performance remains mixed, as the ramp-up of manufacturing and component shortages weigh on operational efficiency and profitability in DCT. Overall, I'm still encouraged by the operational progress made during the quarter as we enter the end of the year. Looking further ahead, my initial time as CEO has strengthened my conviction in the future opportunities for Munters.
Strong demand and continued order growth
DCT was a major contributor, with order intake more than doubling year-on-year, outpacing growth in an exceptionally strong underlying data center market. This reflects the strength of our broadened and highly competitive product portfolio, deep application expertise and continued commercial success. DCT continues to win orders across products and customers, with the US remaining our main stronghold. We are also encouraged by increasing traction in EMEA and early progress in Asia despite DCT's still limited presence in the region.
AirTech's order intake also grew during the quarter, continuing a positive trend over the last 12 months. This was driven by a positive development in APAC and Europe, while activity in the Americas normalized on a good level after a temporary peak in demand for components during the second quarter. FoodTech saw softer demand, driven by project timing and more cautious investment activity in some end-markets.
Translating order growth into sales and earnings
To deliver on our commitments, we are scaling DCT's manufacturing capacity to an entirely new level after expanding our campus in Daleville, Virginia. The overall development remains broadly in line with our original plan to reach significantly higher production volumes towards the end of the year. While external factors such as component availability have affected the pace of the ramp-up, we ended the quarter at a clearly higher level of efficiency and volume than where we started.
This is beginning to show in the top line. DCT's net sales increased 15% year-on-year and around 30% sequentially - an impressive achievement by the team given the ongoing challenges. However, as is normal in an industrial scale-up process such as this, improvements in profitability take somewhat longer to achieve, which is reflected in DCT's EBITA margin being below our ambitions. We still have work to do to reach our desired level of operational efficiency, and constraints in parts of the supply chain and tariff effects continued to weigh on profitability in the quarter. The supply-chain situation has partly improved, although constraints remain industry-wide and need to be taken into account going forward.
AirTech continued its broad-based positive development. Higher volumes, improved capacity utilization and the measures taken to reduce the cost base contributed to improved profitability. Compared with last year, the adjusted EBITA margin increased by close to 6 p.p., of which approx. 2.5 p.p. was a favorable impact related to a non-recurring order cancellation fee. In total, AirTech's profit more than doubled in the third quarter.
FoodTech performed well during the quarter, with continued solid earnings level. The process to explore a potential divestment of the business is progressing according to plan and we will provide further updates in due course.
Outlook and priorities going forward
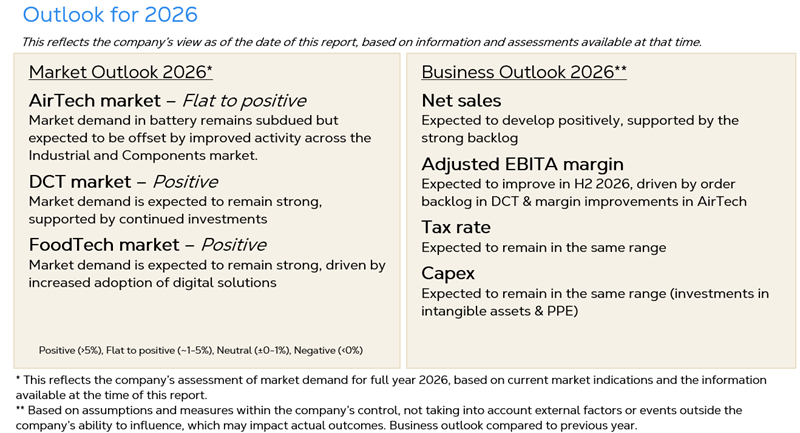
The outlook for 2026 remains unchanged. This is based on the progress made over the year, and the last weeks' gradual and steady improvements in volumes and operational efficiency. We see no underlying change to the attractive long-term trends across our key markets and there is substantial untapped potential in developing our positions around selected climate control applications. On behalf of the management team, I look forward to welcoming you to our Capital Markets Day on November 11, where we will share more about our future strategic direction.
Travelling and spending more time with our businesses across the group, meeting our people and customers, strengthens my conviction in the opportunities ahead for Munters. At the same time, we need to be disciplined about where we focus our resources and ensure we keep translating growth into earnings. We have made good progress, but there is more to do. That is where my attention is, and that is where our teams remain focused.
Finally, I would like to thank my colleagues across Munters for their hard work and for the warm welcome I have received in my new role. I take on the responsibility of leading Munters with great respect for what has been built and confidence in what lies ahead.
Stefan Aspman
President & CEO
?Information about the webcast and telephone conference
Welcome to join a webcast or telephone conference on October 23, at 9:00 CEST, when President and CEO, Stefan Aspman, together with Group Vice President and CFO, Katharina Fischer, will present the report.
Webcast: https://munters.events.inderes.com/q3-report-2026
Telephone conference: If you wish to participate via teleconference, please register on the link below. After registration you will be provided phone numbers and a conference ID to access the conference. You can ask questions verbally via the teleconference. https://events.inderes.com/munters/q3-report-2026/dial-in
This interim report, presentation material and a link to the webcast will be available on https://www.munters.com/en-se/investors/
For more information:
Investors and analysts
Line Dovärn, GVP Investor & Corporate Relations
E-mail: line.dovarn@munters.com, Phone: +46 (0)730 488 444
Media
Daniel Frykholm, VP External Relations & Internal Communications
E-mail: daniel.frykholm@munters.com, Phone: +46 (0)702 067 786
This information is information that Munters Group AB is obliged to make public pursuant to the EU Market Abuse Regulation. The information was submitted for publication, through the agency of the contact persons set out above, at 07.30 CEST on October 23, 2026.
About Munters Group
Munters is a global leader in energy-efficient air treatment and climate solutions. Using innovative technologies, Munters creates the perfect climate for customers in a wide range of industries. Munters has been defining the future of air treatment since 1955. Today, around 5,500 employees carry out manufacturing and sales in more than 25 countries. Munters Group AB reported annual net sales of approx. SEK 15 billion in 2025 and is listed on Nasdaq Stockholm. For more information, please visit www.munters.com.
